Fin-X Weekly Update 12th October 2026

Global bond yields hit new highs early last week before easing, allowing equities to resume
gains. The technology sector led despite concerns about the sustainability of AI spending resurfacing.
The FOMC minutes revealed broad support for another rate increase this year, as the White House renewed pressure on the central bank.
India raised interest rates, while Brazilian markets surged after an unexpected election result.
This week brings US inflation and Australian employment data, the start of the quarterly earnings season, and the IMF and World Bank annual meetings.
Rising bond yields dominated markets early last week. The 10yr US Treasury yield reached a new 24-year high ahead of an auction that eventually saw strong demand. Pressure on bond yields then eased, allowing equities to make renewed gains, led by technology.
The S&P 500 closed above 7,800 for the first time, despite relatively narrow breadth. The Nasdaq Composite and the broader MSCI AC World index remained close to all-time highs, while the S&P/ASX 300 traded at levels first reached in August 2025.
Credit spreads widened modestly in high yield and emerging-market US dollar debt, while investment-grade credit held up relatively better, suggesting that investors continue to rotate towards quality.
Oil prices remained elevated, with West Texas Intermediate crude futures at nearly US$92 per barrel and Brent crude futures above US$104. However, price rises slowed after President Trump said on Friday that Russian President Vladimir Putin had agreed to supply diesel to both the US and global markets, seemingly contravening a sanctions bill he signed into law just a few weeks ago.
The top story in the Australian market was the decision by data centre start-up Firmus Grid to shelve its IPO plans for now, with a private funding round being considered instead.
The Financial Times reported that OpenAI’s annualised revenue was US$20 billion below previously signalled levels, with the company on track for roughly US$50 billion. The miss in expectations sent AI related stocks lower.

Investors are increasingly looking for evidence that revenue can keep pace with the investment required to develop and run AI models, as elevated borrowing costs make the vast sums flowing into data centres and computing infrastructure harder to justify. OpenAI’s revenue revived concerns about the sustainability of the artificial-intelligence spending boom, even after Samsung Electronics estimated that its third-quarter operating profit topped 100 trillion won for the first time in the company’s history. Samsung reported preliminary operating profit of 107.4 trillion won, with more detailed results due later this month.

Despite the record results, Samsung trails its memory peers Micron and SK Hynix. Whereas their shares have soared 151% and 57% respectively, Samsung's shares have only grown 17% year to date.
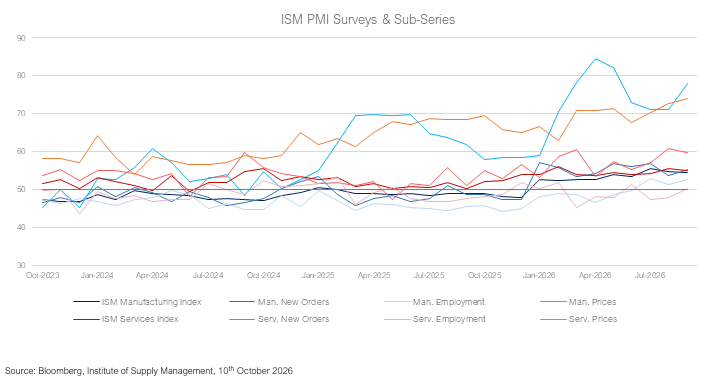
The ISM services survey remained in clear expansion at 54.9, with robust new orders at 59.8 and employment back in expansion at 50.1. However, as in manufacturing, high prices paid (74.0) remain a significant concern.
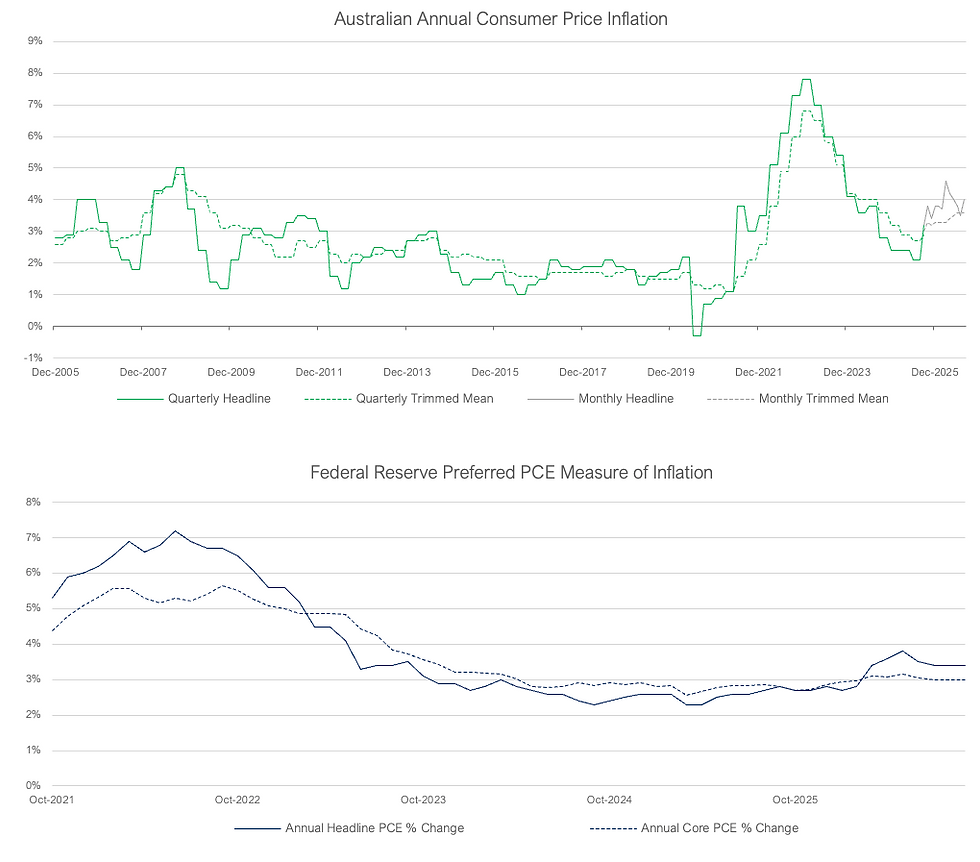
The minutes of the most recent Federal Reserve meeting suggested that FOMC members broadly agree interest rates will need to rise again this year, but gave no indication whether the Fed funds rate would rise in October or December. With the midterm elections due on 3rd November, investors see a December increase as more likely. A reasonably heavy data calendar may test that view this week, including a likely pickup in September CPI inflation.

The White House may once again be trying to pressure the Fed after the President assembled a three-person committee to examine whether Governor Lisa Cook made false statements that could lead to her removal. A hearing is scheduled for 5th November. The move follows the Supreme Court’s five-four ruling in June that Ms Cook could remain in her position because the President failed to allow her to properly dispute his attempt to fire her.
It was also announced that Judy Shelton, whom the Senate blocked from joining the Federal Reserve,
has been appointed a counsellor to Treasury Secretary Scott Bessent. Ms Shelton, an outspoken supporter of restoring a relationship between the US dollar and gold, will advise Mr Bessent on currency policy, “with a particular focus on evaluating financial conditions in China”, the Treasury said in a statement.
In emerging markets, the Reserve Bank of India unanimously raised its policy repo rate by +0.25% to 5.50%, its first increase since February 2023. The RBI is expected to raise rates again at its next meeting in December.
In Brazil’s presidential election, right-wing challenger Flávio Bolsonaro unexpectedly led incumbent Luiz Inácio Lula da Silva by roughly 47% to 45%. Mr Bolsonaro is the son of former president Jair Bolsonaro, who is currently serving a sentence under humanitarian house arrest for attempting to overturn the 2022 election result. As neither candidate secured a majority, they will contest a runoff on 25th October.
Mr Bolsonaro is seen as the more business-friendly candidate, and the Ibovespa surged to a record, up +8.8% for the week, while the real appreciated +4.3% in US dollar terms.
Australian unemployment for September is expected to hold at 4.6% when released on Thursday. The rate ticked up in August on slightly higher participation, but job advertisements continue to rise. Westpac consumer confidence nevertheless softened. The NAB business confidence survey will be updated tomorrow.
A large volume of global production data is also due this week. Wall Street banks, including Goldman Sachs, JPMorgan, Citigroup and Wells Fargo, kick off the quarterly earnings season. In addition, the IMF and World Bank will hold their annual meetings in Bangkok, where discussions are likely to focus on the outlook for growth, inflation, interest rates, and government debt.


Disclaimer
The contents of this communication are prepared by Fin-X Capital Group Pty Ltd (A.C.N. 627 650 293; AFSL 520526 trading as Fin-X Capital). The information contained in this communication is general in nature and does not take into consideration any investors personal objectives, goals, needs and financial situation. You should not rely on the information contained in this document to make any investment decisions without first consulting an investment professional such as your financial adviser. Any unauthorised use of this document is prohibited. This document (including any attachments) is intended only for the addressee, it may contain information of a privileged and confidential nature. If you are not the addressee of this communication, you must not copy, reproduce, disseminate or use this email and its contents. If this communication has been received in error by you, please inform us immediately and securely delete. Sharing, transmitting, copying, disseminating all or part of the contents of this document may result in a breach of the Federal Privacy Legislation and or copyright and trademark infringement of Fin-X Capital Group Pty Ltd and its related entities.