Fin-X Weekly Update 7th September 2026
Global equities remained near record highs while bond yields rose on hawkish central bank speeches and rising commodity prices.
Energy prices jumped as tensions between the United States and Iran escalated, with Washington broadening its economic pressure.
US labour data proved stronger than anticipated, while subdued Australian Q2 growth was accompanied by early signs of firmer growth this quarter.
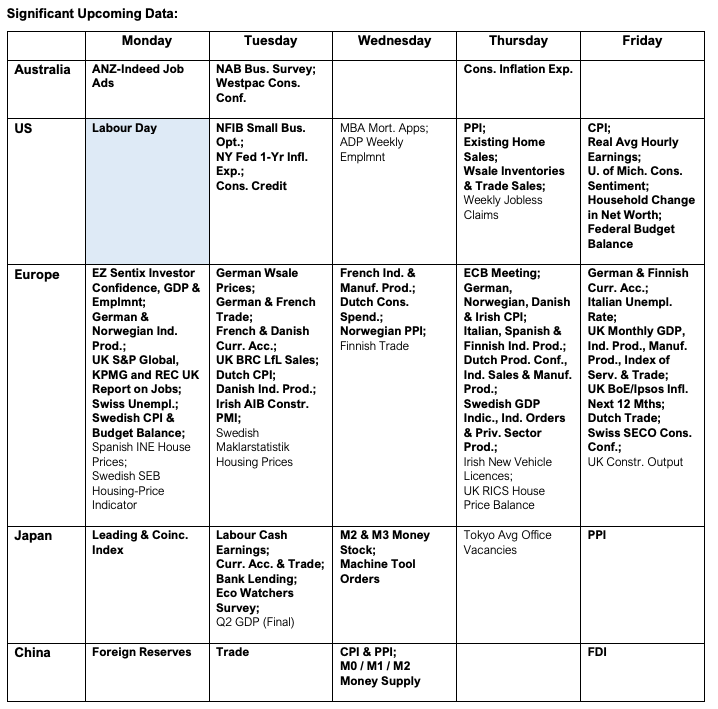
This week brings US and Chinese inflation, a European rate decision, and Australian business and consumer confidence surveys.

Risk assets began last week on the back foot as investors digested a more hawkish Jackson Hole speech by Federal Reserve Chairman Kevin Warsh. Higher commodity prices, together with a strong US jobs report on Friday, applied further upward pressure to bond yields.
The US carried out strikes against IRGC targets, and Iran responded with missile and drone attacks. Treasury Secretary Scott Bessent said the Strait of Hormuz would be “worthless” in two years once exporters find workarounds. However, any such shift appeared some way off as WTI moved above US$90 and Brent closed above US$96 per barrel.
Coal prices posted a double-digit increase and European natural gas rose to its highest level since January 2023. Mr Bessent praised the EU for formally joining “Operation Economic Outcast”, as Washington widened its pressure on Iran to the economic front. Higher prices supported energy and some commodities-linked stocks, while rate-sensitive growth and technology names lagged, contributing to early-week declines in the Nasdaq.
The Nasdaq Composite subsequently recovered, adding +1.4% on Thursday after influential FOMC member Christopher Waller said he would support keeping rates on hold later this month.

Technology sentiment was further supported by the launch of four new frontier AI models. OpenAI released GPT-6 Astra, Meta introduced Muse Spark 1.3, and Anthropic unveiled Fable 5.1 alongside its invitation-only twin, Mythos 5.1. Google likewise released Gemini 3.8 Flash and a restricted Cyber variant.

OpenAI will hope their GPT-6 Astra model sways users as new data from Bloomberg and accounting software provider Ramp shows that its usage has stalled in the past year and a half. Both OpenAI and Anthropic are looking to impress the public as they both aim for an IPO later this year.
Early US data were mixed. The July JOLTS job openings (7.3 million), ISM manufacturing orders (53.7) and construction spending (-0.5%) all came in on the weaker side, while factory orders (+0.9%) and ISM services orders (60.9) exceeded forecasts.
Friday's labour report saw the unemployment rate hold at 4.1%, in line with expectations, but the detail was consistently firmer than anticipated. Participation rose from 61.4% to 61.6%, average weekly hours increased to 34.4, and the underemployment rate fell from 7.9% to 7.7%. July's surprisingly weak change in non-farm payrolls of -23k was revised up to +21k, while the initial August estimate of +162k comfortably surpassed the +55k consensus forecast.

The addition of 162k jobs comes as the US labour force added roughly 683k workers in August, the highest since January 2025.
Equities closed slightly lower in Friday's Wall Street session, though the overall reaction was relatively subdued ahead of the long weekend. For bond investors, attention now turns to this Friday's CPI figures. The monthly headline reading is likely to be firmer in August, but annual headline CPI is expected to hold at +3.4%, while economists polled by Bloomberg expect core CPI to slow from +2.5% to +2.4%.
In Australia, real GDP grew by just +0.4%, only very slightly above the +0.3% figure for Q1. The subdued first-half momentum risks being over-interpreted as a weak signal. Early third-quarter data suggest growth could be accelerating and broadening, supported by private-sector investment and relatively high wage awards, which can also lift participation and household-spending multipliers. Private credit growth was slightly slower in August than in July but remained close to its post-GFC highs at +8.4% yoy, driven by business borrowing. At the same time, Melbourne Institute inflation accelerated
from +4.0% yoy to +4.8% yoy in August.
The RBNZ raised the cash rate by a quarter point to 2.75% on Wednesday, as anticipated.
In the euro area, flash inflation estimates for several member states and an area-wide reading of 3.3% yoy underscored the persistence of energy and food components, even as underlying measures gradually converge towards target, cooling from +2.5% yoy in July to +2.4% in August. The ECB is expected to raise rates by +0.25% to 2.5% on Thursday.
In China, the official manufacturing (49.8) and non-manufacturing (49.0) PMIs remained in contractionary territory, while the RatingDog equivalents indicated slight expansion at 51.5 and 51.4, respectively. Later this week, CPI and PPI figures are expected to show continued acceleration at +0.9% yoy and +3.6% yoy.
Following the meeting of G20 finance ministers and central bank governors in Asheville, North Carolina, there was little news to move markets. The Chairman's Statement centred on debt sustainability and burden-sharing, “responsible and effective” regulation of digital assets, and reaffirmed support for FATF standards on money laundering and terrorism
financing; China objected to several paragraphs.
US markets are closed for Labour Day today. In addition to the American and Chinese inflation figures and the European Central Bank meeting later this week, Australian job ads are due today, with the NAB Business Survey and Westpac Consumer Confidence survey to follow tomorrow.


Disclaimer
The contents of this communication are prepared by Fin-X Capital Group Pty Ltd (A.C.N. 627 650 293; AFSL 520526 trading as Fin-X Capital). The information contained in this communication is general in nature and does not take into consideration any investors personal objectives, goals, needs and financial situation. You should not rely on the information contained in this document to make any investment decisions without first consulting an investment professional such as your financial adviser. Any unauthorised use of this document is prohibited. This document (including any attachments) is intended only for the addressee, it may contain information of a privileged and confidential nature. If you are not the addressee of this communication, you must not copy, reproduce, disseminate or use this email and its contents. If this communication has been received in error by you, please inform us immediately and securely delete. Sharing, transmitting, copying, disseminating all or part of the contents of this document may result in a breach of the Federal Privacy Legislation and or copyright and trademark infringement of Fin-X Capital Group Pty Ltd and its related entities.